EUDR Customs Document: Who Is the Consignee and What Are Their Responsibilities?
Published
, 8 minute read
Share this article
Quick summary: EUDR customs document roles explained: learn if the consignee, importer or broker is the EUDR operator and who must link the DDS reference to customs.
EUDR customs document is becoming an important part of the import and export process for businesses dealing with products covered by the EU Deforestation Regulation. One question creates particular confusion: who is responsible when the consignee shown in customs documentation is not the same company that supplied the goods?
Understanding the relationship between the consignee, importer, operator, customs representative and EUDR Due Diligence Statement (DDS) is essential. These roles can overlap, but they should not be treated as automatically identical.
Key Takeaways
The EUDR customs process is connected to the EU customs declaration; it is not a completely separate customs document.
The consignee, importer and EUDR operator can overlap, but the terms should not be treated as automatically identical.
For relevant products imported from outside the EU for release for free circulation, the importer is generally the EUDR operator.
A customs representative can handle customs formalities without automatically becoming the EUDR operator.
The DDS reference or applicable declaration identifier needs to be correctly connected to the customs process.
Businesses should connect EUDR data, products, shipments and customs information rather than managing them as separate records.
Is your supply chain actually ready?
Move from spreadsheets and fragmented supplier data to a traceable, audit-ready EUDR workflow with TraceX.
EUDR does not create a completely separate customs declaration. Instead, EUDR requirements are connected to the EU customs declaration for relevant products. A customs declaration is the official document through which goods are placed under a customs procedure, such as release for free circulation or export.
For relevant products, the customs process must be connected with the applicable DDS reference number or, where applicable, the identifier of a Simplified Declaration. This links the shipment being declared with the EUDR compliance information behind it.
Discover how EUDR requirements interact with customs processes, DDS reference information, product classification, and import/export documentation to help businesses maintain compliant and transparent EU trade workflows.Read the Full Blog→
Who Is the Consignee?
In EU customs terminology, the consignee is the party identified as the recipient in the relevant customs documentation. For EUDR, however, the key question is not simply who receives the goods. European Commission guidance explains that for relevant products produced outside the EU and imported for release for free circulation, the EUDR operator is generally the person acting as the importer. The importer is identified in relevant customs data and may correspond to the consignee in box 8 of the Single Administrative Document.
Therefore, a consignee shown on a transport or commercial document is not automatically the EUDR operator merely because its name appears as the recipient. Businesses should establish who is acting as the importer and who has the EUDR operator responsibility.
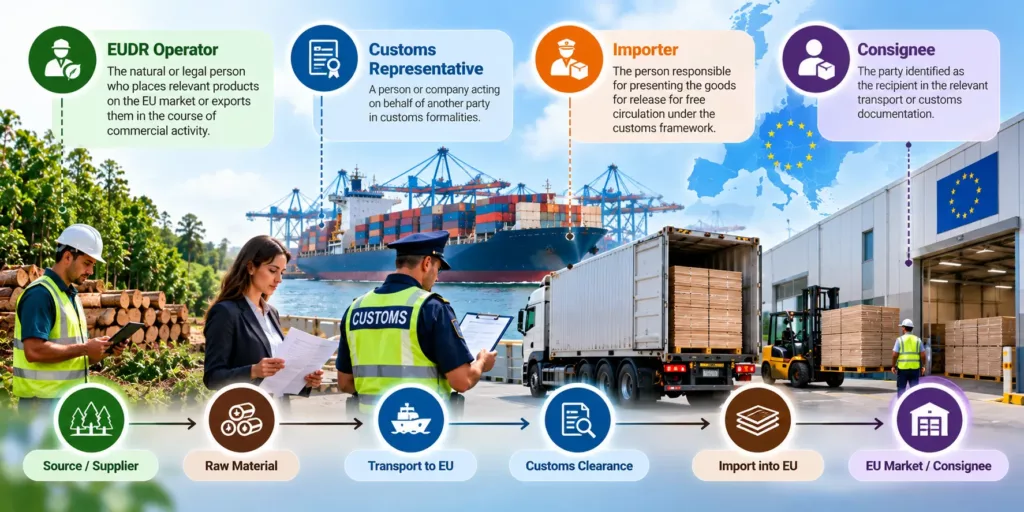
Consignee vs Importer vs EUDR Operator
Consignee: the party identified as the recipient in the relevant transport or customs documentation.
Importer: the person responsible for presenting the goods for release for free circulation under the customs framework.
EUDR operator: the natural or legal person who places relevant products on the EU market or exports them in the course of commercial activity.
Customs representative: a person or company acting on behalf of another party in customs formalities.
For relevant products imported from outside the EU for release for free circulation, Commission guidance links the EUDR operator role to the person acting as importer, including the person identified in relevant customs data or as the consignee in the Single Administrative Document.
What Are the EUDR Responsibilities of the Importer/Operator?
Complete the required EUDR due diligence before placing the relevant product on the EU market.
Collect the required information, including production location and other applicable Article 9 information.
Assess the risk of non-compliance and take risk-mitigation measures where required.
Submit the applicable DDS before placing the relevant product on the EU market, where a DDS is required.
Ensure the relevant DDS reference number or applicable declaration identifier is available for the customs process.
Maintain the required records and supporting evidence for the applicable retention period.
Be able to demonstrate the basis for the EUDR declaration if requested by competent authorities.
Discover who qualifies as an economic operator under the EUDR, what their due diligence responsibilities involve, and how they can manage traceability, risk assessment, documentation, and compliance obligations.Read the Full Blog →
Does the Consignee Need to Submit the DDS?
Not simply because it is named as the consignee. The key question is whether the consignee is the EUDR operator or another party with the relevant legal role.
For an import into the EU, the EUDR operator is generally the person acting as importer when the goods are declared for release for free circulation. Commission guidance specifically explains that this importer can be identified through relevant customs data, including the consignee field in the Single Administrative Document.
Businesses should therefore not design their EUDR workflow around the label ‘consignee’ alone. They should first determine the legal and customs roles for the transaction and then assign the appropriate EUDR responsibilities.
What If the Consignee Is Different From the Buyer?
A common scenario is that an EU company buys goods from a non-EU supplier, while a logistics company, warehouse, distributor or another group entity appears as the consignee. The parties should establish who is acting as the importer for the customs declaration and who is placing the relevant product on the EU market.
EUDR operator status is not determined solely by who owns the goods. Commission guidance states that, for imported relevant products, the definition of operator is independent of a change of ownership and other contractual arrangements.
What Does the Customs Broker Need?
A customs broker or representative may prepare or submit customs formalities on behalf of the importer, but that does not automatically transfer the underlying EUDR operator responsibility. The European Commission explains that customs declarations are usually made by the owner of the goods or a person acting on their behalf, such as a representative.
Operationally, the importer should provide the broker with the correct EUDR information needed for the customs declaration, including the applicable DDS reference number or declaration identifier. The importer should also have controls to ensure that the reference corresponds to the correct product and shipment.
How Technology Can Connect EUDR and Customs
The operational challenge is connecting the EUDR record to the physical shipment. A business may have supplier information, geolocation, legality evidence, risk assessment and DDS data in one system while shipment and customs information sits somewhere else.
A digital EUDR workflow can connect supplier, production location, product, batch, DDS, shipment and customs reference in a single traceability chain. This makes it easier to determine which DDS reference belongs to a shipment, provide it to the customs broker and maintain an audit trail.
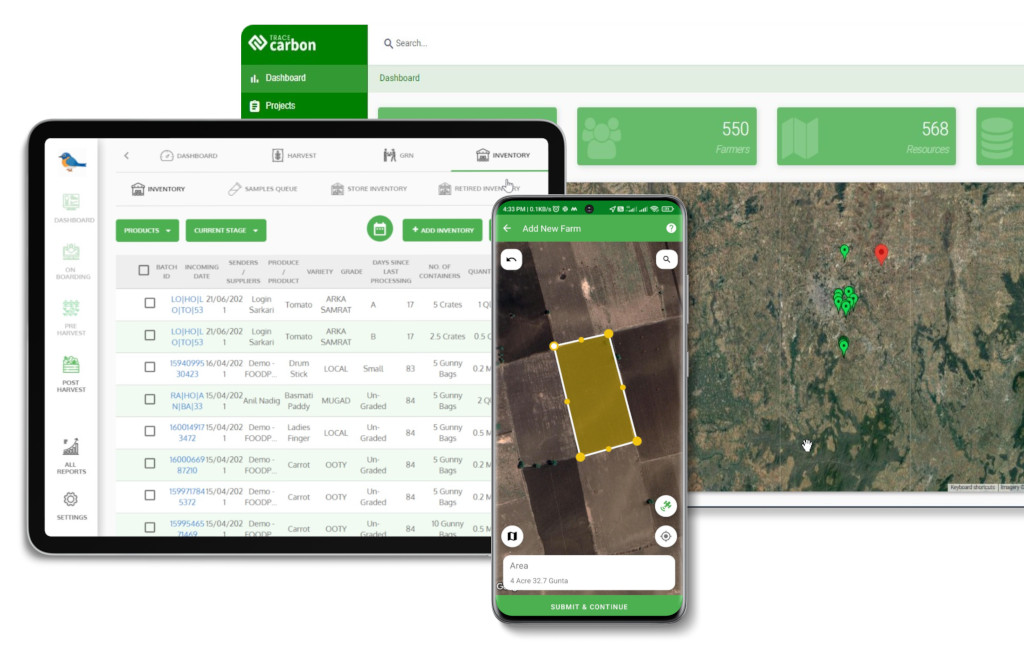
TraceX EUDR Solutions can support this workflow by connecting supplier and source data with product, batch, shipment, compliance evidence and DDS records. This helps businesses move from a standalone DDS approach to a connected process in which EUDR compliance information follows the product through procurement, dispatch and customs.
See how TraceX connects supplier data, geolocation, due diligence, DDS references, products, batches and shipments in one digital EUDR workflow.
Confirm the EU CN/TARIC classification and EUDR scope of the product.
Identify the importer and EUDR operator for the transaction.
Confirm the applicable EUDR due diligence or Simplified Declaration requirement.
Complete the required due diligence and risk assessment.
Generate or obtain the applicable DDS reference number or declaration identifier.
Match the reference to the relevant product, batch and shipment.
Share the required reference with the customs broker or representative.
Validate customs data before submission.
Retain the supporting EUDR evidence and transaction records.
Conclusion
For EUDR compliance, the consignee field should not be viewed in isolation. The important step is to understand who is acting as the importer, who is the EUDR operator, who is representing the importer at customs and how the EUDR reference is connected to the shipment.
As EUDR moves closer to implementation, companies should build a process that connects due diligence with logistics and customs execution. A clear link between supplier evidence, product classification, DDS, shipment and customs declaration can reduce manual errors and make EUDR compliance easier to manage at scale.
Frequently Asked Questions
Is every consignee an EUDR operator?
No. Customs and EUDR roles must be assessed based on the transaction and applicable legal definitions. For imports from outside the EU, the importer for release for free circulation is generally the EUDR operator.
Can the customs broker be the EUDR operator?
A customs representative can act on behalf of the importer for customs formalities. Representation does not, by itself, make the representative the EUDR operator.
Does the non-EU supplier need to submit the EU customs declaration?
Not necessarily. The customs declaration and EUDR operator roles depend on the import arrangement. A non-EU supplier may provide the underlying EUDR data and evidence to the EU operator.
Does the consignee need the DDS verification number?
The EUDR Information System distinguishes the DDS reference number from the verification number. Businesses should follow the applicable Information System and customs requirements rather than treating the verification number as a replacement for the DDS reference.
What if the wrong DDS reference is provided to customs?
The reference should correspond to the relevant EUDR compliance record and shipment. Businesses should build validation controls before customs submission to reduce mismatches and delays.
Start using TraceX
Transparency, Trust, & Success for your Climate Journey.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Download the 2026 Traceability Scorecard and Benchmark Your Supply Chain Across 10 Critical Capabilities.
Download our eBook
Don’t Wait for an Audit to Find Your EUDR Gaps
The 2026 Simplification Package changes how HS codes, DDS pass-through and geolocation rules apply to you. Get the free guide and 20-point readiness checklist before enforcement catches you unprepared.