Quick summary: EUDR scope explained: the seven commodities, Annex I products, and the July 2026 delegated act changes — plus how to confirm if your products are in scope.
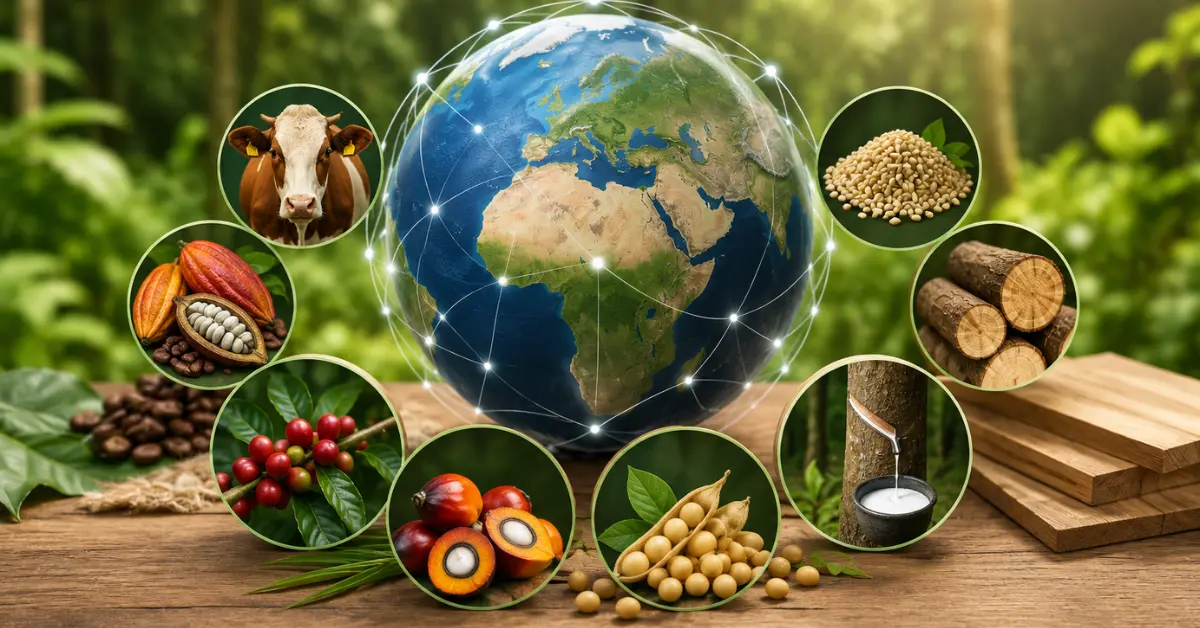
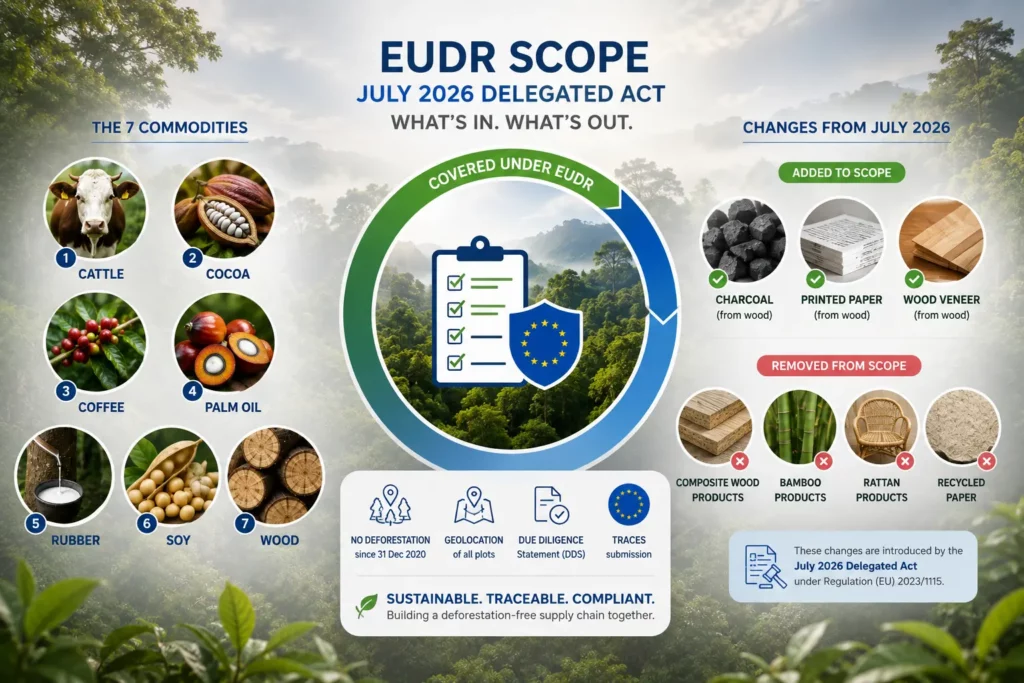
EUDR scope defines which commodities and products must be proven deforestation-free before they are placed on the EU market. It covers seven commodities cattle, cocoa, coffee, oil palm, rubber, soy and wood plus the derived products listed in Annex I of Regulation (EU) 2023/1115. On 13 July 2026 the Commission adopted a Delegated Act amending Annex I: soluble coffee, a range of palm oil derivatives, soap and frozen cattle tongue are pulled into scope (applying from 30 December 2027), while cattle hides, skins and leather are taken out. The seven commodities and the core deadlines 30 December 2026 for large and medium operators, 30 June 2027 for micro and small are unchanged.
Key takeaways
The EUDR scope is set by Annex I: seven commodities plus specific derived products, identified by CN code. If a product is not listed in Annex I, it is not regulated even if it contains a covered commodity.
The 13 July 2026 Delegated Act adds 17 product codes (incl. soluble coffee, palm oil derivatives, soap, frozen cattle tongue), deletes cattle leather (HS 4101/4104/4107), and clarifies exemptions.
Newly added products apply from 30 December 2027 one year after the general application date.
The seven commodities, the 30 Dec 2026 / 30 June 2027 deadlines and the 31 December 2020 cut-off have not changed.
The Delegated Act is adopted but not yet in force it is in a two-month Parliament and Council scrutiny period.
Check Your EUDR Scope and identify which products may require due diligence before you start preparing your compliance data.
Use our tool to quickly assess whether your products may fall within the Regulation based on their product category and HS code.
EUDR scope refers to the exact set of commodities and products that the EU Deforestation Regulation covers — the goods you must prove are deforestation-free and legally produced before selling them in, or exporting them from, the EU. It is the first question every business asks, and the one that decides whether the rest of the regulation applies to you at all.
Two layers define it. First, the seven regulated commodities: cattle, cocoa, coffee, oil palm, rubber, soy and wood. Second, and this is where most businesses get caught out, the EUDR scope is fixed by Annex I of Regulation (EU) 2023/1115 — a list of specific derived products, each identified by its CN (Combined Nomenclature) code. A product is only in scope if its code appears in Annex I. Conversely, products whose codes are not listed are outside the rules, even if they contain a covered commodity.
Getting this wrong is expensive in both directions. Read the list too narrowly and you place a non-compliant product on the EU market, risking blocked shipments and fines. Read it too broadly and you burn resources collecting geolocation and filing statements for products that were never covered. A precise, code-level reading is what keeps you on the right side of both.
The “ex” prefix in Annex I matters too: it means only part of a code’s products are caught. For example, under a furniture code only the wooden seats are regulated, not the metal ones. This is why a scope check is a code-by-code exercise, not a commodity-by-commodity guess.
EUDR scope: the seven commodities and who is caught
Within that product list, the regulation catches three groups of businesses, defined by role rather than sector:
Operators
Any person or company that places a relevant product on the EU market for the first time, or exports it typically importers and EU manufacturers. Operators carry full due diligence and file the Due Diligence Statement (DDS).
Traders and downstream operators
Businesses that further distribute in-scope products inside the EU. Under the December 2025 amendment, most downstream actors rely on an upstream DDS rather than filing a fresh one, but they still sit inside the regulation’s reach.
Operator, downstream operator or trader? Understanding your EUDR role is critical to knowing what information you need to collect, who files the DDS and where your responsibility begins and ends.
In commodity terms that means chocolate and confectionery (cocoa), coffee brands and roasters, palm oil in food, cosmetics and biofuels, soy in animal feed and processed foods, natural rubber and tyres, beef and cattle products, and timber, furniture, pulp and paper. If your business touches any of these, a scope check is not optional it is the starting point for market access. And note the common trap: holding a sustainability certification such as Rainforest Alliance or FSC does not settle the question. Certifications support risk mitigation, but scope is decided by the product code in Annex I, not by the label on the pack.
The latest EUDR scope changes: the July 2026 Delegated Act
This is the update every business needs to re-check against. On 13 July 2026 the European Commission adopted a Delegated Act amending Annex I, alongside Implementing Regulation (EU) 2026/1565 governing the EU Information System. Both build on the December 2025 amendment (Regulation (EU) 2025/2650) and complete the simplification package proposed in May 2026. They do not reopen the regulation itself — they redraw the product list, which is exactly where EUDR scope lives.
The Delegated Act makes three kinds of change (17 codes added, 3 deleted, 1 clarified in the draft assessment of 31 codes):
Pulled into scope (apply from 30 December 2027)
Soluble (instant) coffee and other previously-excluded coffee derivatives.
A range of palm oil derivatives (oleochemicals), plus soap bars and flakes — closing a well-known loophole.
Frozen cattle (bovine) tongue and related beef derivatives.
The pattern is clear: the additions pull downstream and derivative products into scope where they were previously unregulated despite being made from a covered commodity. Because these are new, they apply one year later, from 30 December 2027.
Taken out of scope
Cattle hides, skins and leather (HS 4101, 4104 and 4107) are removed — the headline deletion, driven by trade-flow and enforceability concerns.
Retreaded tyres are narrowed (obligations focus on the new tread), and several other rubber and vehicle-component lines are trimmed.
Clarified exemptions
The act confirms what is explicitly outside the regulation — waste, used and end-of-life goods, reusable packaging and correspondence — removing longstanding ambiguity. One important caveat: the Delegated Act is adopted but not yet in force. It is in a two-month scrutiny period before the European Parliament and the Council, so treat the direction as settled but confirm the final Annex I text before you lock decisions.
The companion Implementing Regulation (EU) 2026/1565 matters too. It rewrites the rules for the EU Information System — the TRACES-based platform through which operators submit due diligence statements and simplified declarations. So the July 2026 package changes both which products are covered and how the evidence for them is filed, which is why a scope review and a systems review belong together, not in separate quarters.
The EUDR Delegated Act can have a direct impact on how companies interpret product scope, obligations and compliance workflows.
Amid the scope churn, the anchors are stable. The core deadlines run by operator size, not by a single date:
30 December 2026 — large and medium operators and traders.
30 June 2027 — micro and small operators and traders.
30 December 2027 — the products newly added by the July 2026 Delegated Act.
31 December 2020 — the deforestation cut-off. It is a property of the land and has never moved through any postponement.
One earlier scope change is worth remembering: the December 2025 amendment already removed printed products books, newspapers and other printing-industry goods on paper from Annex I. Together with the July 2026 act, the practical message is that the EUDR scope is a moving list, and last year’s mapping is not this year’s.
How to confirm your EUDR scope position
For most businesses the whole regulation reduces to one question: is my product still on the list? Confirming your EUDR scope position is a data exercise matching every product line and feedstock against the amended Annex I by CN code, not by finished-product name.
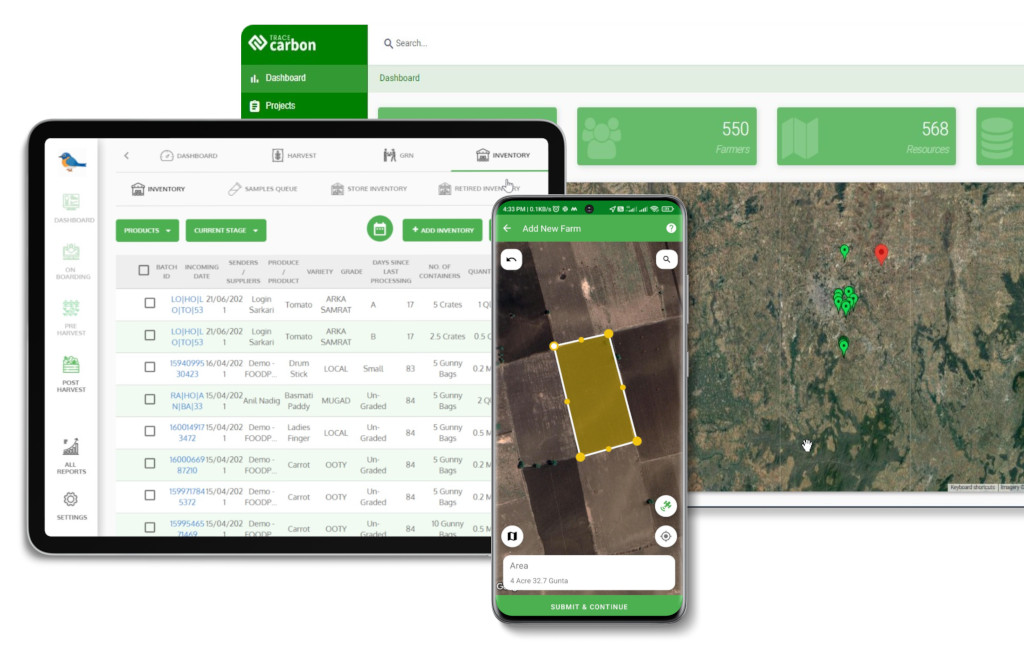
This is where a single traceability layer earns its keep. TraceX maps your product portfolio to the current Annex I codes, flags lines pulled newly into scope, and links each in-scope product to the supplier, geolocation and DDS evidence it will need. Instead of re-reading the regulation every time the Commission amends the list, your EUDR scope mapping stays live the same data foundation that later answers CSDDD, CSRD and buyer due-diligence questions.
The proof point for a buyer: when the scope list changes again and it will you re-run a mapping in minutes rather than commissioning a fresh legal review across your entire catalogue.
Composite and multi-commodity products are where this gets hardest. A single SKU can contain wood, palm oil and soy at once, each with its own code, supplier and origin. Mapping at the component level and knowing which components were pulled in or out by the latest amendment is precisely the work that a structured system removes, and precisely where manual spreadsheets quietly break down.
Treating EUDR scope as a one-time check is the mistake that creates last-minute scrambles. Between the December 2025 amendment, the July 2026 Delegated Act and the reviews still to come, the product list is deliberately dynamic. The businesses that win map their catalogue to Annex I codes once, in a system that updates when the list does so a scope change becomes a filter, not a fire drill.
EUDR scope after the July 2026 Delegated Act: in, out, clarified
The seven commodities; 30 Dec 2026 / 30 Jun 2027; 31 Dec 2020 cut-off
Core obligations and dates stand
TraceX EUDR Solutions helps businesses simplify EUDR scope assessment and compliance by mapping products against applicable HS codes, identifying relevant commodities and products, and connecting scope decisions with supplier, geolocation, traceability and due-diligence data. With a centralised platform, companies can move from “Is this product in scope?” to “Do we have the evidence to comply?”while managing supplier data, plot-level geolocation, risk assessment, mitigation and DDS readiness in one workflow.
See how TraceX maps your catalogue to the amended Annex I, flags lines newly in or out of scope, and links each in-scope product to the evidence it needs well before 30 December 2026.
See how TraceX maps your catalogue to the amended Annex I
Also Flags lines newly in or out of scope, and links each in-scope product to the evidence it needs well before 30 December 2026.
Buyer’s checklist: choosing a tool for EUDR scope mapping
When you evaluate a platform for EUDR scope mapping and compliance, these questions separate a real solution from a static spreadsheet:
Does it map your product catalogue to Annex I by CN code, not just by commodity name?
Does it update automatically when the Commission amends Annex I, and flag lines newly in or out of scope?
Can it distinguish operator, trader and downstream-operator obligations for each in-scope line?
Does it link each in-scope product to its geolocation, legality evidence and DDS reference?
Does it keep an audit-ready, exportable record for five years?
Will the same data foundation serve CSDDD, CSRD and buyer questionnaires, so you build once?
frequently asked questions
What is the scope of the EUDR?
The EUDR scope covers seven commodities cattle, cocoa, coffee, oil palm, rubber, soy and wood and the derived products listed by CN code in Annex I of Regulation (EU) 2023/1115. A product is only in scope if its code is listed; products not in Annex I are outside the rules even if they contain a covered commodity.
How do I know if my product is in EUDR scope?
Match each product line to Annex I by its CN code, then check whether that line was added, removed or clarified by the July 2026 Delegated Act. Finished-product names are not reliable scope is determined at code level, and the “ex” prefix means only part of a code may be caught.
What changed in the July 2026 delegated act?
It amends Annex I: adding products such as soluble coffee, palm oil derivatives, soap and frozen cattle tongue (applying from 30 December 2027); removing cattle hides, skins and leather (HS 4101/4104/4107); narrowing retreaded tyres; and clarifying exemptions for waste, used goods, reusable packaging and correspondence.
Are the new products in scope immediately?
No. Products newly added by the July 2026 Delegated Act apply from 30 December 2027 one year after the general application date of 30 December 2026 to give businesses time to prepare.
Did the EUDR deadlines change with the scope update?
No. The core dates are unchanged: 30 December 2026 for large and medium operators and traders, and 30 June 2027 for micro and small. The 31 December 2020 deforestation cut-off is also unchanged.
Is soap or leather still in EUDR scope?
This reverses the old position. Soap and palm oil derivatives are being added to scope by the July 2026 Delegated Act, while cattle leather is being removed. Any guidance that still says “soap with palm oil is exempt” predates this change.
Is the July 2026 delegated act final?
It has been adopted by the Commission but is not yet in force it is in a two-month scrutiny period before the European Parliament and the Council. Treat the scope direction as settled in substance, but confirm the final Annex I text and exact CN codes before locking decisions.
Start using TraceX
Transparency, Trust, & Success for your Climate Journey.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Download the 2026 Traceability Scorecard and Benchmark Your Supply Chain Across 10 Critical Capabilities.
Download our eBook
Don’t Wait for an Audit to Find Your EUDR Gaps
The 2026 Simplification Package changes how HS codes, DDS pass-through and geolocation rules apply to you. Get the free guide and 20-point readiness checklist before enforcement catches you unprepared.