Challenges in the Ethiopian Coffee Sector: Why Traceability Now Decides EU Market Access
Published
, 7 minute read
Share this article
Quick summary: Challenges in Ethiopian coffee sector: climate, market access, labor, and EUDR compliance risks — and how traceability protects EU market access.
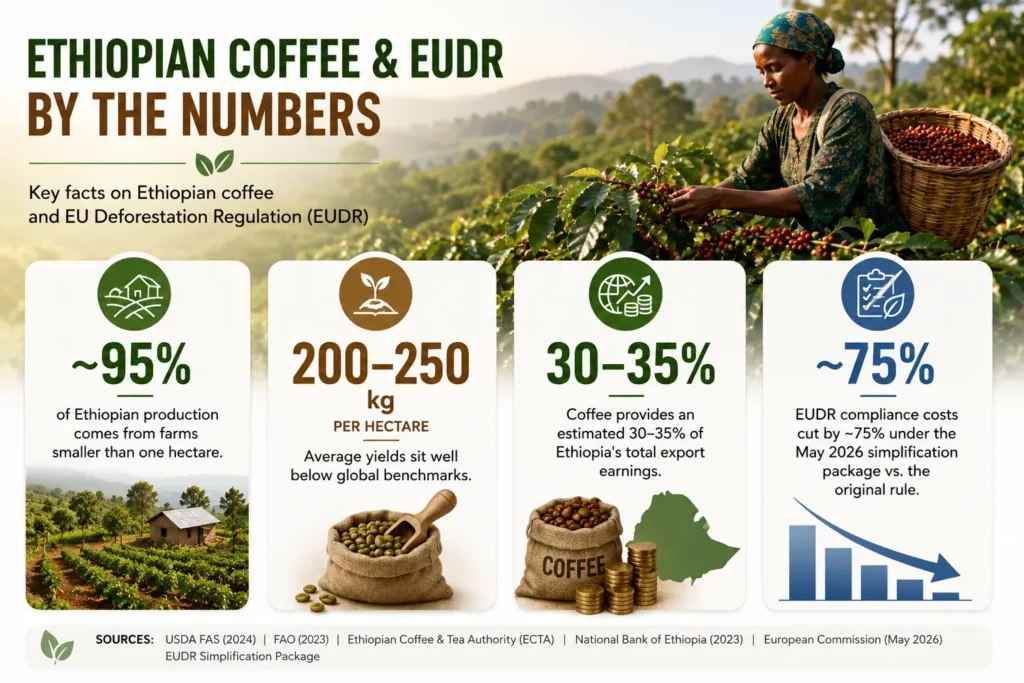
The main challenges in the Ethiopian coffee sector are climate change and deforestation, price volatility and weak market access, social and labor pressures from an aging farming population, and a rising compliance burden above all the EU Deforestation Regulation (EUDR), which from 30 December 2026 requires plot-level geolocation and a due diligence statement for coffee sold into the EU. Because Ethiopia’s sector is ~95% smallholder-driven, the hardest of these is proving deforestation-free origin. Exporters who adopt digital traceability protect EU market access and win premium buyers; those who cannot risk losing contracts.
The challenges in Ethiopian coffee sector are, at their root, a proof problem wearing several disguises. Ethiopia is the birthplace of coffee and Africa’s largest producer, yet behind every specialty cup sits a fragmented, largely smallholder supply chain now facing climate stress, price volatility, and the toughest market-access rules it has ever seen. For exporters, cooperatives, and the buyers who source from them, the stakes are concrete: coffee generates an estimated 30–35% of Ethiopia’s export earnings, and much of that revenue depends on continued access to Europe.
In plain terms, the challenges in Ethiopian coffee sector are the obstacles environmental, economic, social, and regulatory that stand between Ethiopia’s heritage beans and the premium global markets that reward them. The four groups below are ordered from long-standing to most urgent.
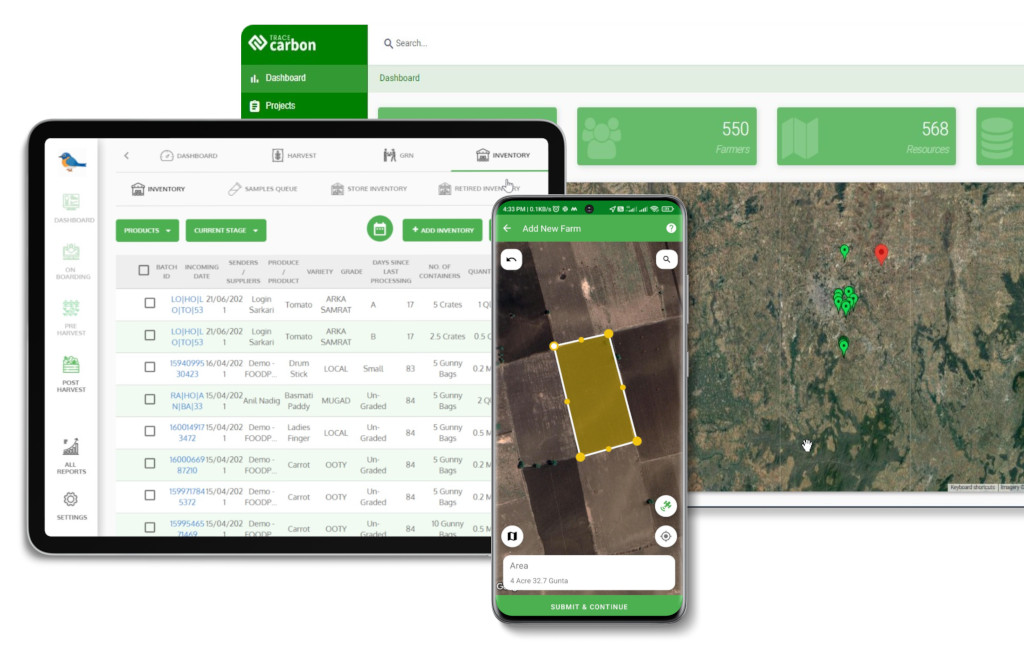
Simplify every stage of EUDR compliance—from supplier onboarding and geolocation verification to risk assessments and Due Diligence Statement (DDS) submission—with a unified, audit-ready platform.
The challenges in Ethiopian coffee sector cluster into four areas: climate and deforestation, economics and market access, social and labor, and regulatory compliance.
EUDR is now the decisive commercial risk: no plot-level geolocation and no filed DDS means no EU market access from 30 December 2026.
A ~95% smallholder base makes farm-level data collection the core bottleneck and the biggest opportunity.
Certifications help but do not satisfy EUDR on their own; digital traceability that captures geolocation and generates a DDS is what unlocks premium contracts.
Climate Change and Deforestation: The Environmental Challenges in Ethiopian Coffee
Rising temperatures, erratic rainfall, and extreme weather are shifting the microclimates that Ethiopia’s Arabica depends on, cutting both yield and quality. At the same time, coffee-linked deforestation and land degradation erode the shade-forest ecosystems that traditionally protect the crop. This is not only an agronomic threat under EUDR, any coffee grown on land deforested after 31 December 2020 is barred from the EU market entirely. Climate-resilient varieties, agroforestry, and sustainable land management help, but each depends on knowing exactly where and how each lot was grown. Among the challenges in Ethiopian coffee sector, this environmental exposure is the one that now carries direct market consequences.
Economic Constraints and Market Access Challenges in the Ethiopian Coffee Sector
Volatile world prices make farmer income unpredictable and often fail to cover the cost of production. Limited access to finance keeps smallholders from investing in the inputs, infrastructure, and data systems that would raise productivity and quality. The result is a paradox: Ethiopia grows world-class coffee but captures a shrinking share of the value chain. Fair-trade and direct-trade models, microfinance, and market diversification all help but the fastest route to a higher price today is verifiable, traceable coffee that buyers can trust. Of all the challenges in Ethiopian coffee sector, weak margins are the hardest to fix without first fixing visibility.
Social and Labor Challenges Facing Ethiopian Coffee Farmers
Youth migration to cities is leaving an aging farming population, raising real questions about who will grow Ethiopia’s coffee in a decade. Many workers also face low wages and limited access to social protection, healthcare, and education. Youth-engagement programs, better working conditions, and community development are the long-term answers and increasingly, buyers want evidence that these commitments are real, not asserted. That, again, is a data-and-documentation question, and it links the social challenges in Ethiopian coffee sector back to the same traceability backbone every other issue relies on.
Regulatory and EUDR Compliance Challenges in the Ethiopian Coffee Sector
This is where the challenges in Ethiopian coffee sector become existential. European buyers no longer ask only about taste they ask where the coffee was grown, whether it can be proven deforestation-free, and whether the supply chain is compliant. With EUDR applying from 30 December 2026 for large and medium operators (and 30 June 2027 for micro and small ones), a great bean is no longer enough.
Without plot-level geolocation and a filed due diligence statement, exporters risk losing lucrative EU contracts some already have when their data did not hold up under scrutiny.
Buyers often layer on Organic, Fairtrade, or Rainforest Alliance requirements as well. Important nuance: these certifications support risk mitigation, but they do not replace EUDR’s geolocation, plot-level evidence, or DDS obligations. The market is now rewarding exporters who can pull up real-time, verifiable data on demand traceability and compliance have become the ticket to market access, not optional extras.
Manual Records vs. Digital Traceability: Solving the Challenges in Ethiopian Coffee
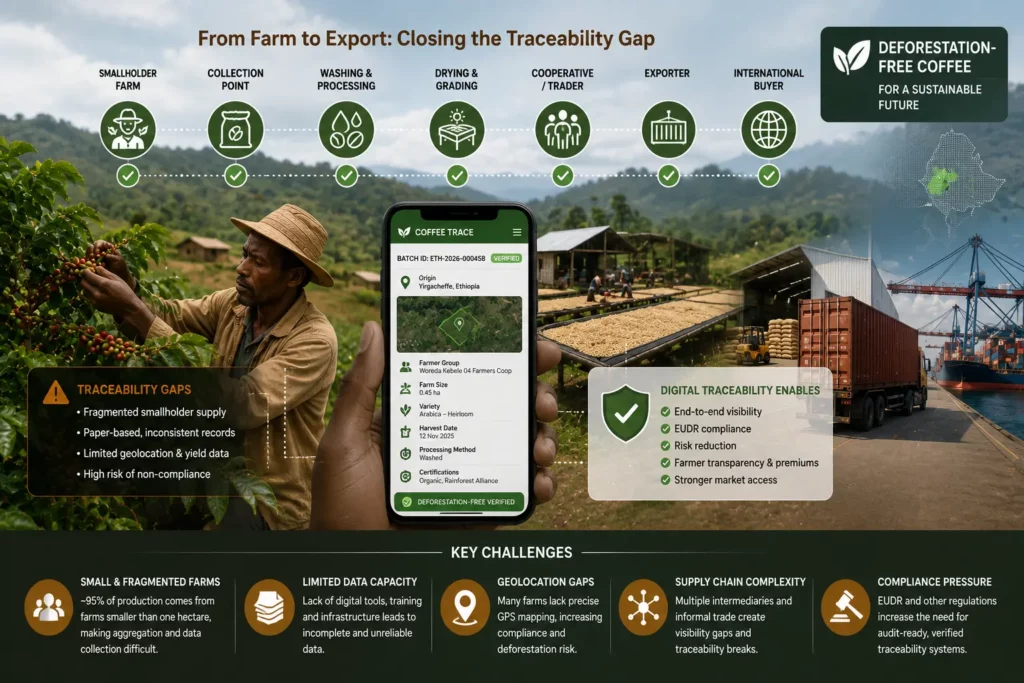
Many of the challenges in Ethiopian coffee sector converge on one operational choice — how a coffee exporter manages data. The gap between losing and winning EU contracts increasingly comes down to it:
Requirement
Manual / paper records
Digital traceability platform
Farm geolocation
Missing or approximate
GPS + polygon at plot level
Deforestation check
Guesswork
Satellite-verified, flagged in real time
DDS for EUDR
Manual, error-prone
Auto-generated, submission-ready
Smallholder onboarding
Slow, inconsistent
Structured, app-based
Audit trail
Fragile paperwork
Tamper-proof, immutable
EU market access
At risk
Protected
How TraceX Helps Ethiopian Coffee Exporters Overcome These Challenges
Technology does not remove the challenges in Ethiopian coffee sector, but it makes them manageable. The pain is clear: a ~95% smallholder base and paper records cannot meet EUDR’s evidentiary bar. The capability that answers it is an end-to-end EUDR compliance platform that collects farm geolocation, scores supplier risk, and auto-generates a due diligence statement ready for the EU Information System. The benefit is direct: fewer shipment rejections at EU ports, faster smallholder onboarding, and buyer trust backed by tamper-proof proof of deforestation-free sourcing
Protect your EU market access
See how TraceX turns smallholder coffee sourcing into audit-ready, EUDR-compliant proof.
The proof point: a Nigerian trading firm sourcing cocoa and cashew used TraceX’s EUDR platform to eliminate data-collection errors from farmers and local agents, achieve end-to-end traceability, and safeguard EU compliance.
EUDR-Readiness Checklist for Ethiopian Coffee Exporters
Before your next EU shipment, confirm you can:
Capture GPS coordinates and polygon maps for every sourcing plot
Prove no deforestation on that land after 31 December 2020
Generate and file a due diligence statement to the EU Information System
Onboard smallholders and cooperatives at scale, with clean data
Produce a tamper-proof audit trail linking each lot to its origin
Meet buyer certification asks without treating them as EUDR substitutes
Frequently Asked Questions
Why is traceability such a major challenge in the Ethiopian coffee sector?
Because the sector is roughly 95% smallholder-driven with limited digital infrastructure, collecting the farm-level geolocation data that traceability and EUDR require is difficult and slow which is exactly the gap digital platforms close.
How does the EU’s EUDR regulation impact Ethiopian coffee exports?
From 30 December 2026, coffee sold into the EU must be deforestation-free, backed by plot-level GPS mapping and a filed due diligence statement. Without that proof, Ethiopian exporters risk losing access to one of their largest markets.
Do Organic or Rainforest Alliance certifications satisfy EUDR for Ethiopian coffee?
No. They support sustainability and risk mitigation but do not replace EUDR’s geolocation, plot-level evidence, or due diligence statement obligations, which must be met independently.
What technologies help overcome the challenges in Ethiopian coffee sector?
Digital traceability platforms, satellite deforestation monitoring, and AI-driven risk assessment let exporters map farms, flag risks early, and auto-generate EUDR-compliant reports protecting market access and buyer trust.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Download the 2026 Traceability Scorecard and Benchmark Your Supply Chain Across 10 Critical Capabilities.
Download our eBook
Don’t Wait for an Audit to Find Your EUDR Gaps
The 2026 Simplification Package changes how HS codes, DDS pass-through and geolocation rules apply to you. Get the free guide and 20-point readiness checklist before enforcement catches you unprepared.